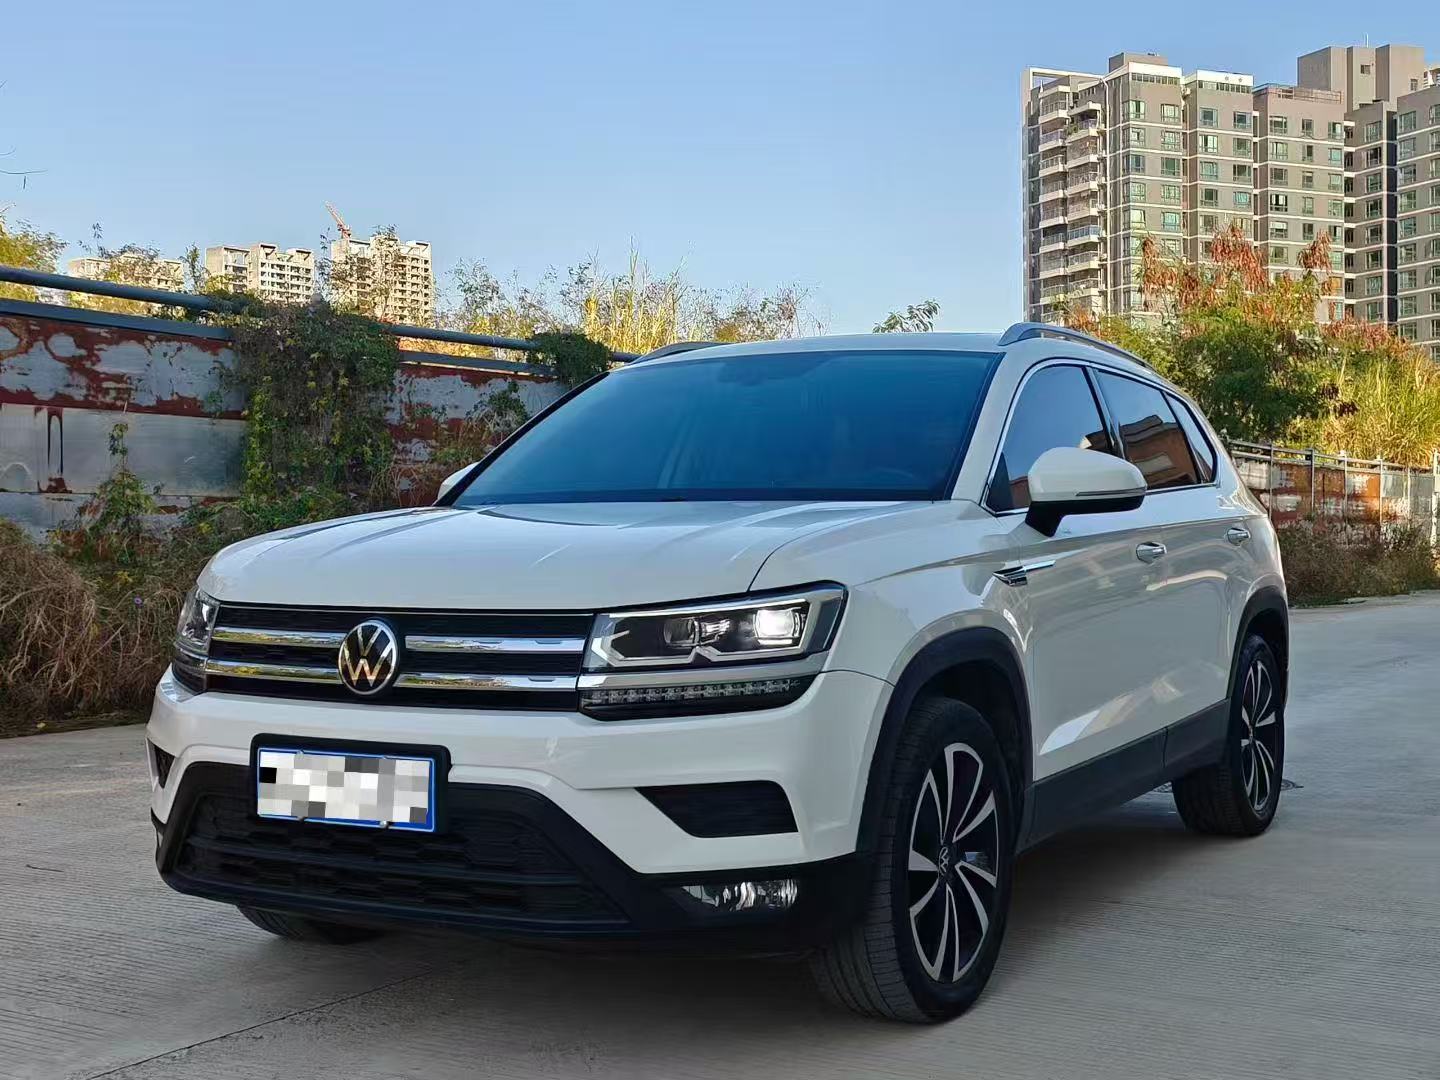
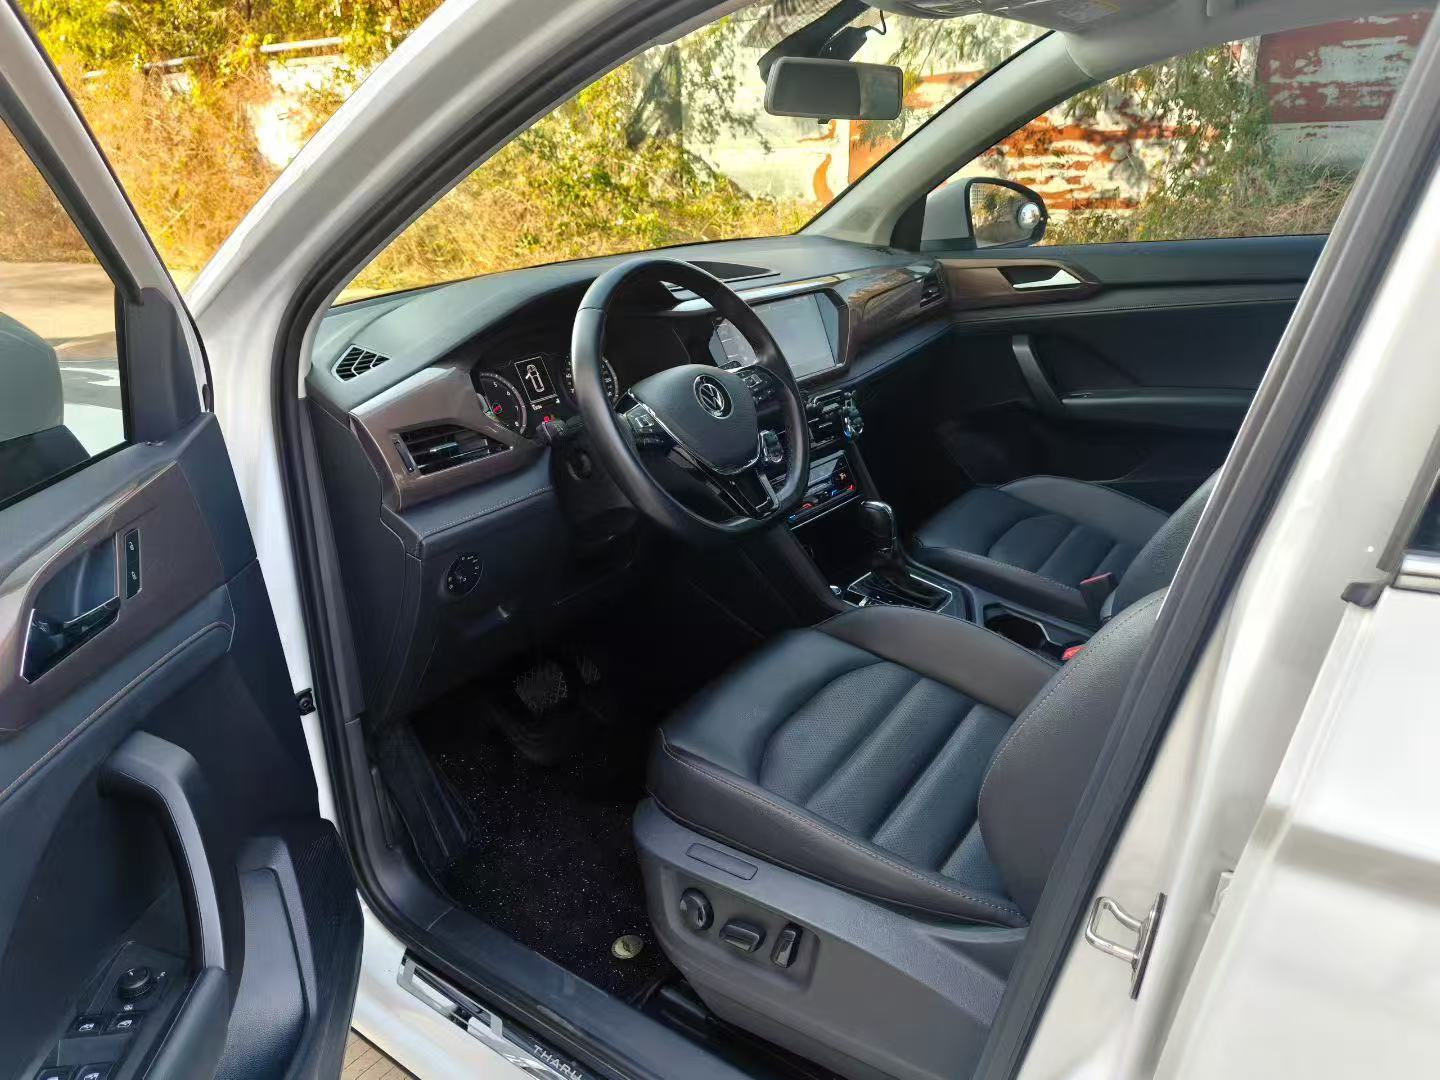
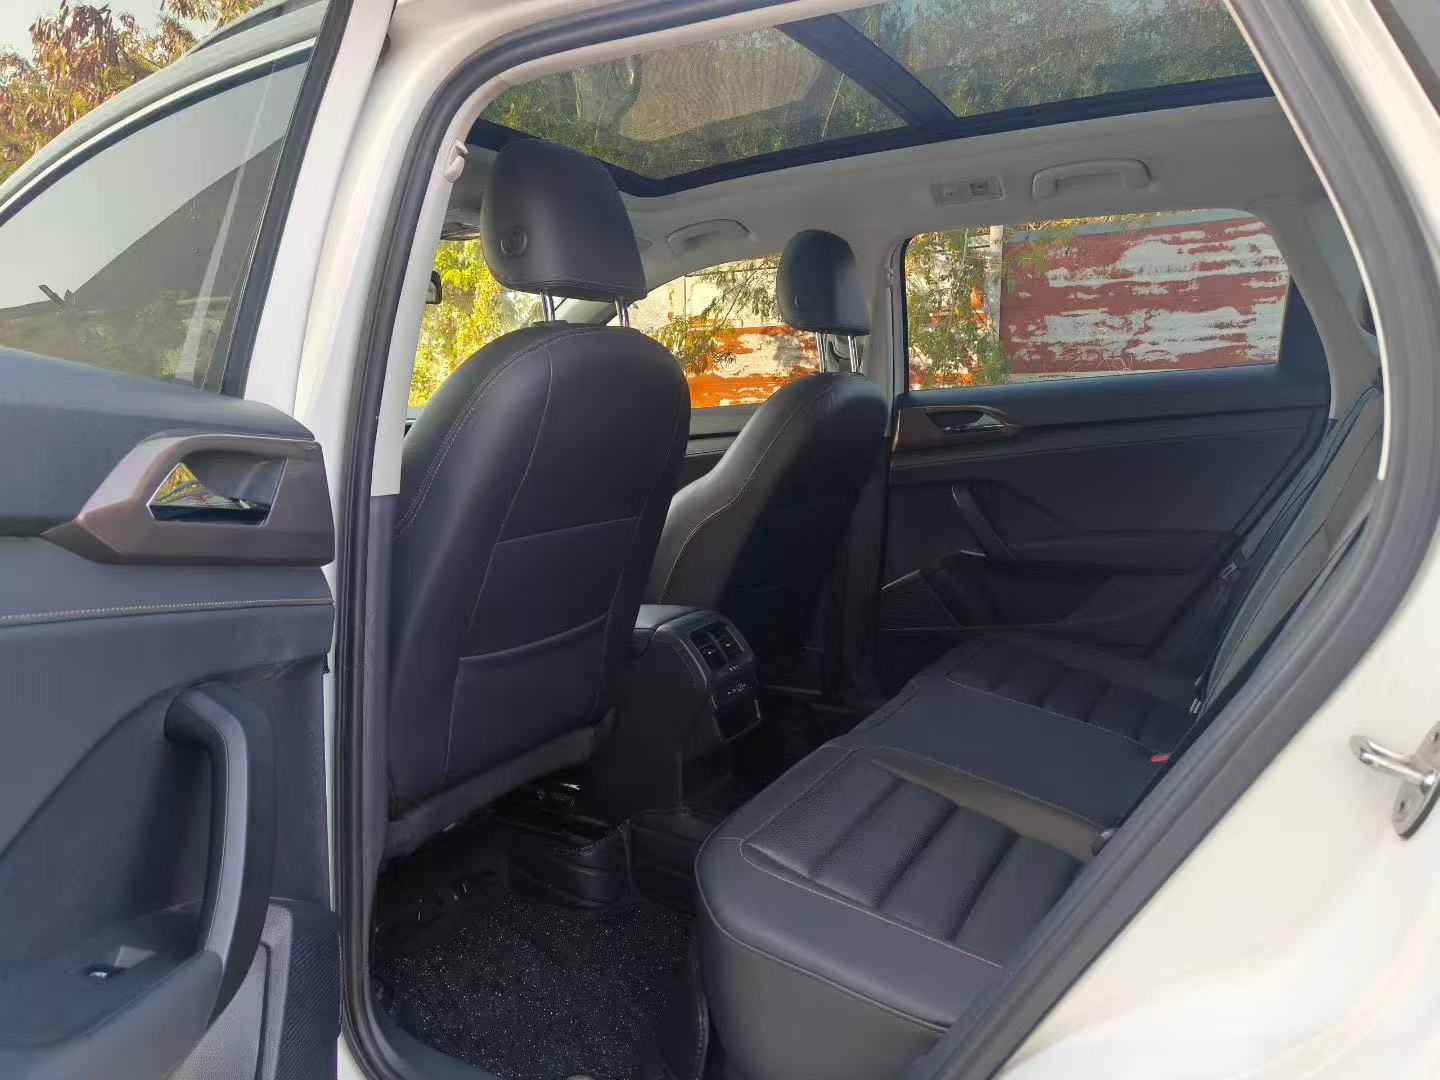
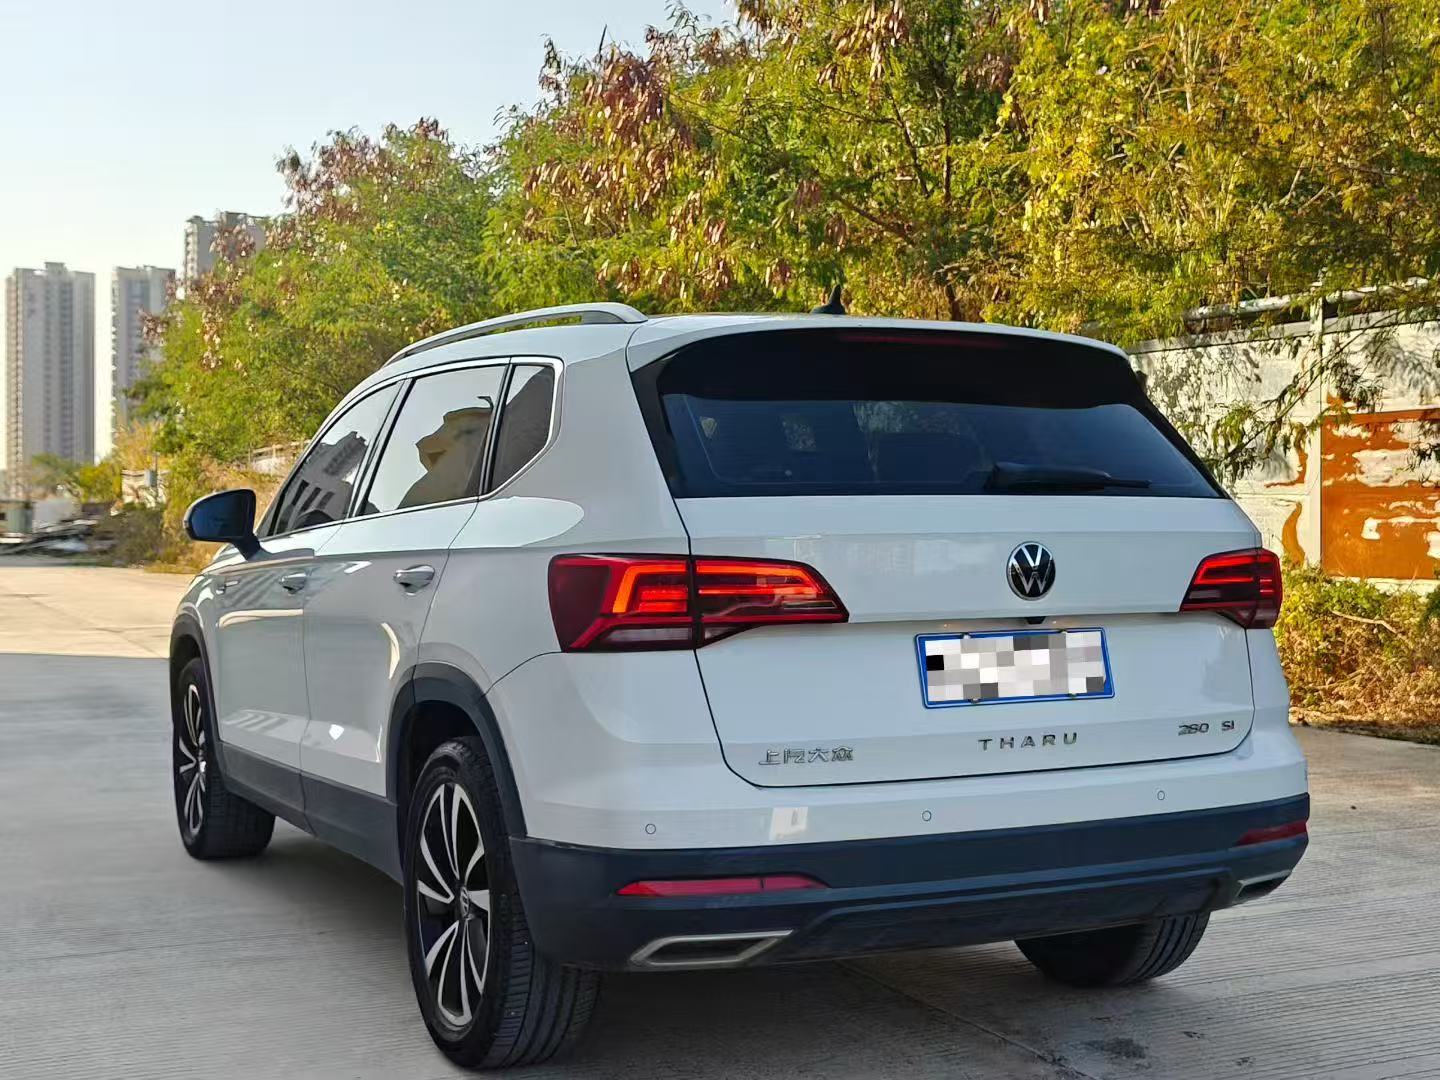
Basic Information

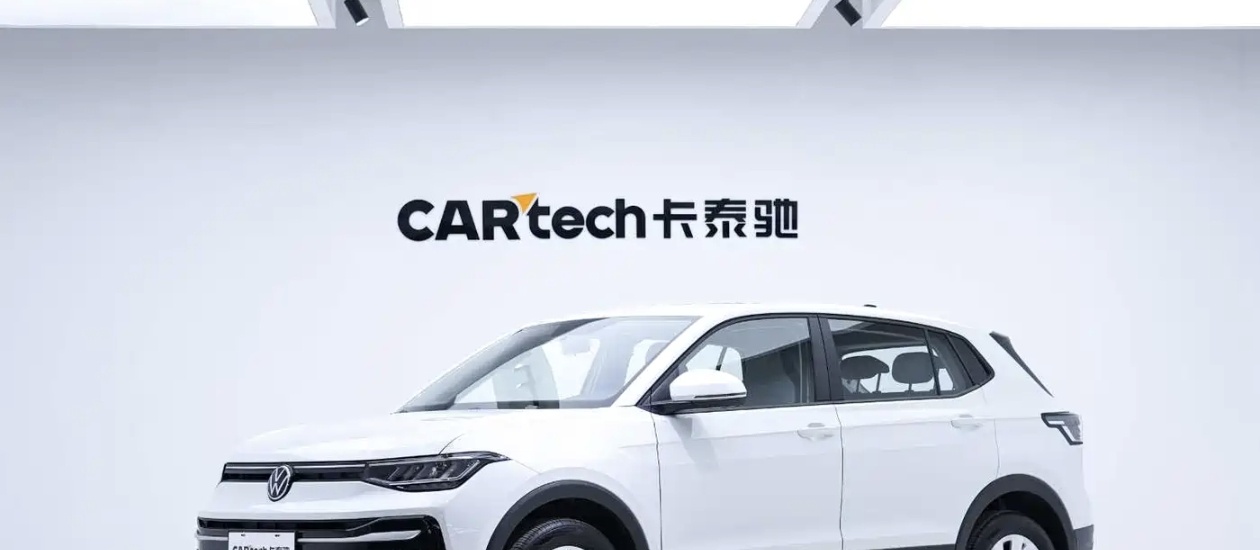
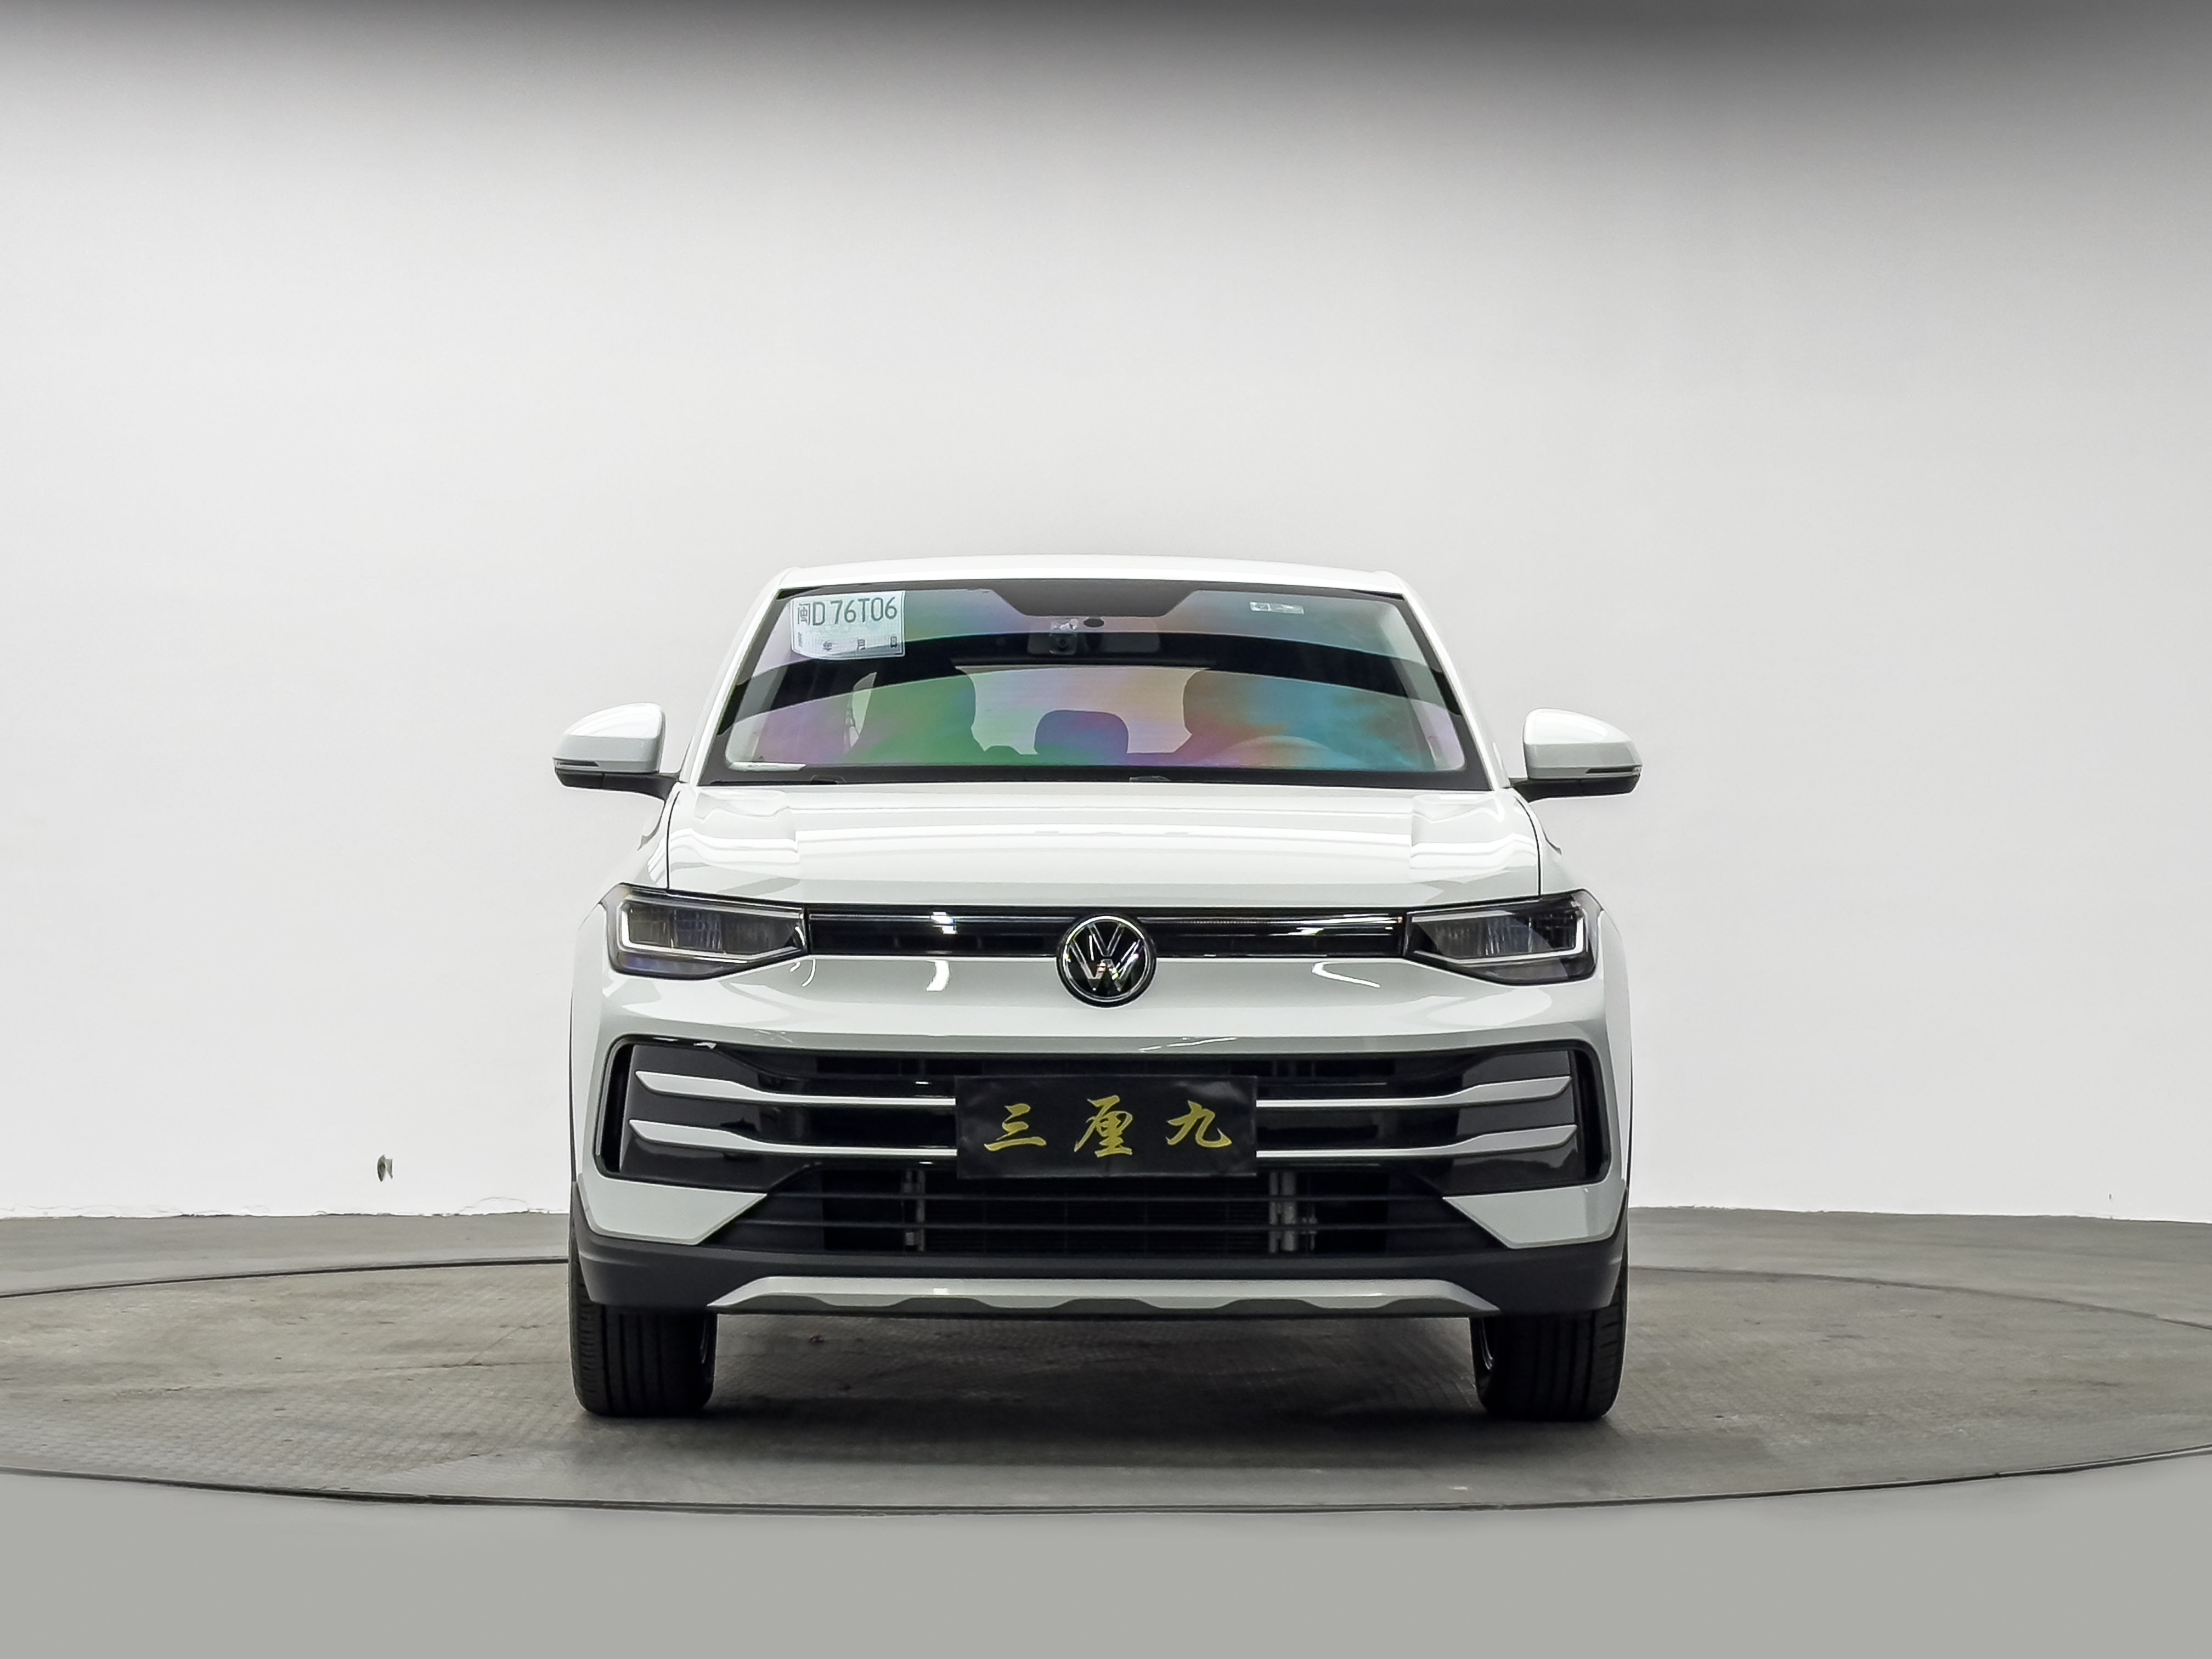
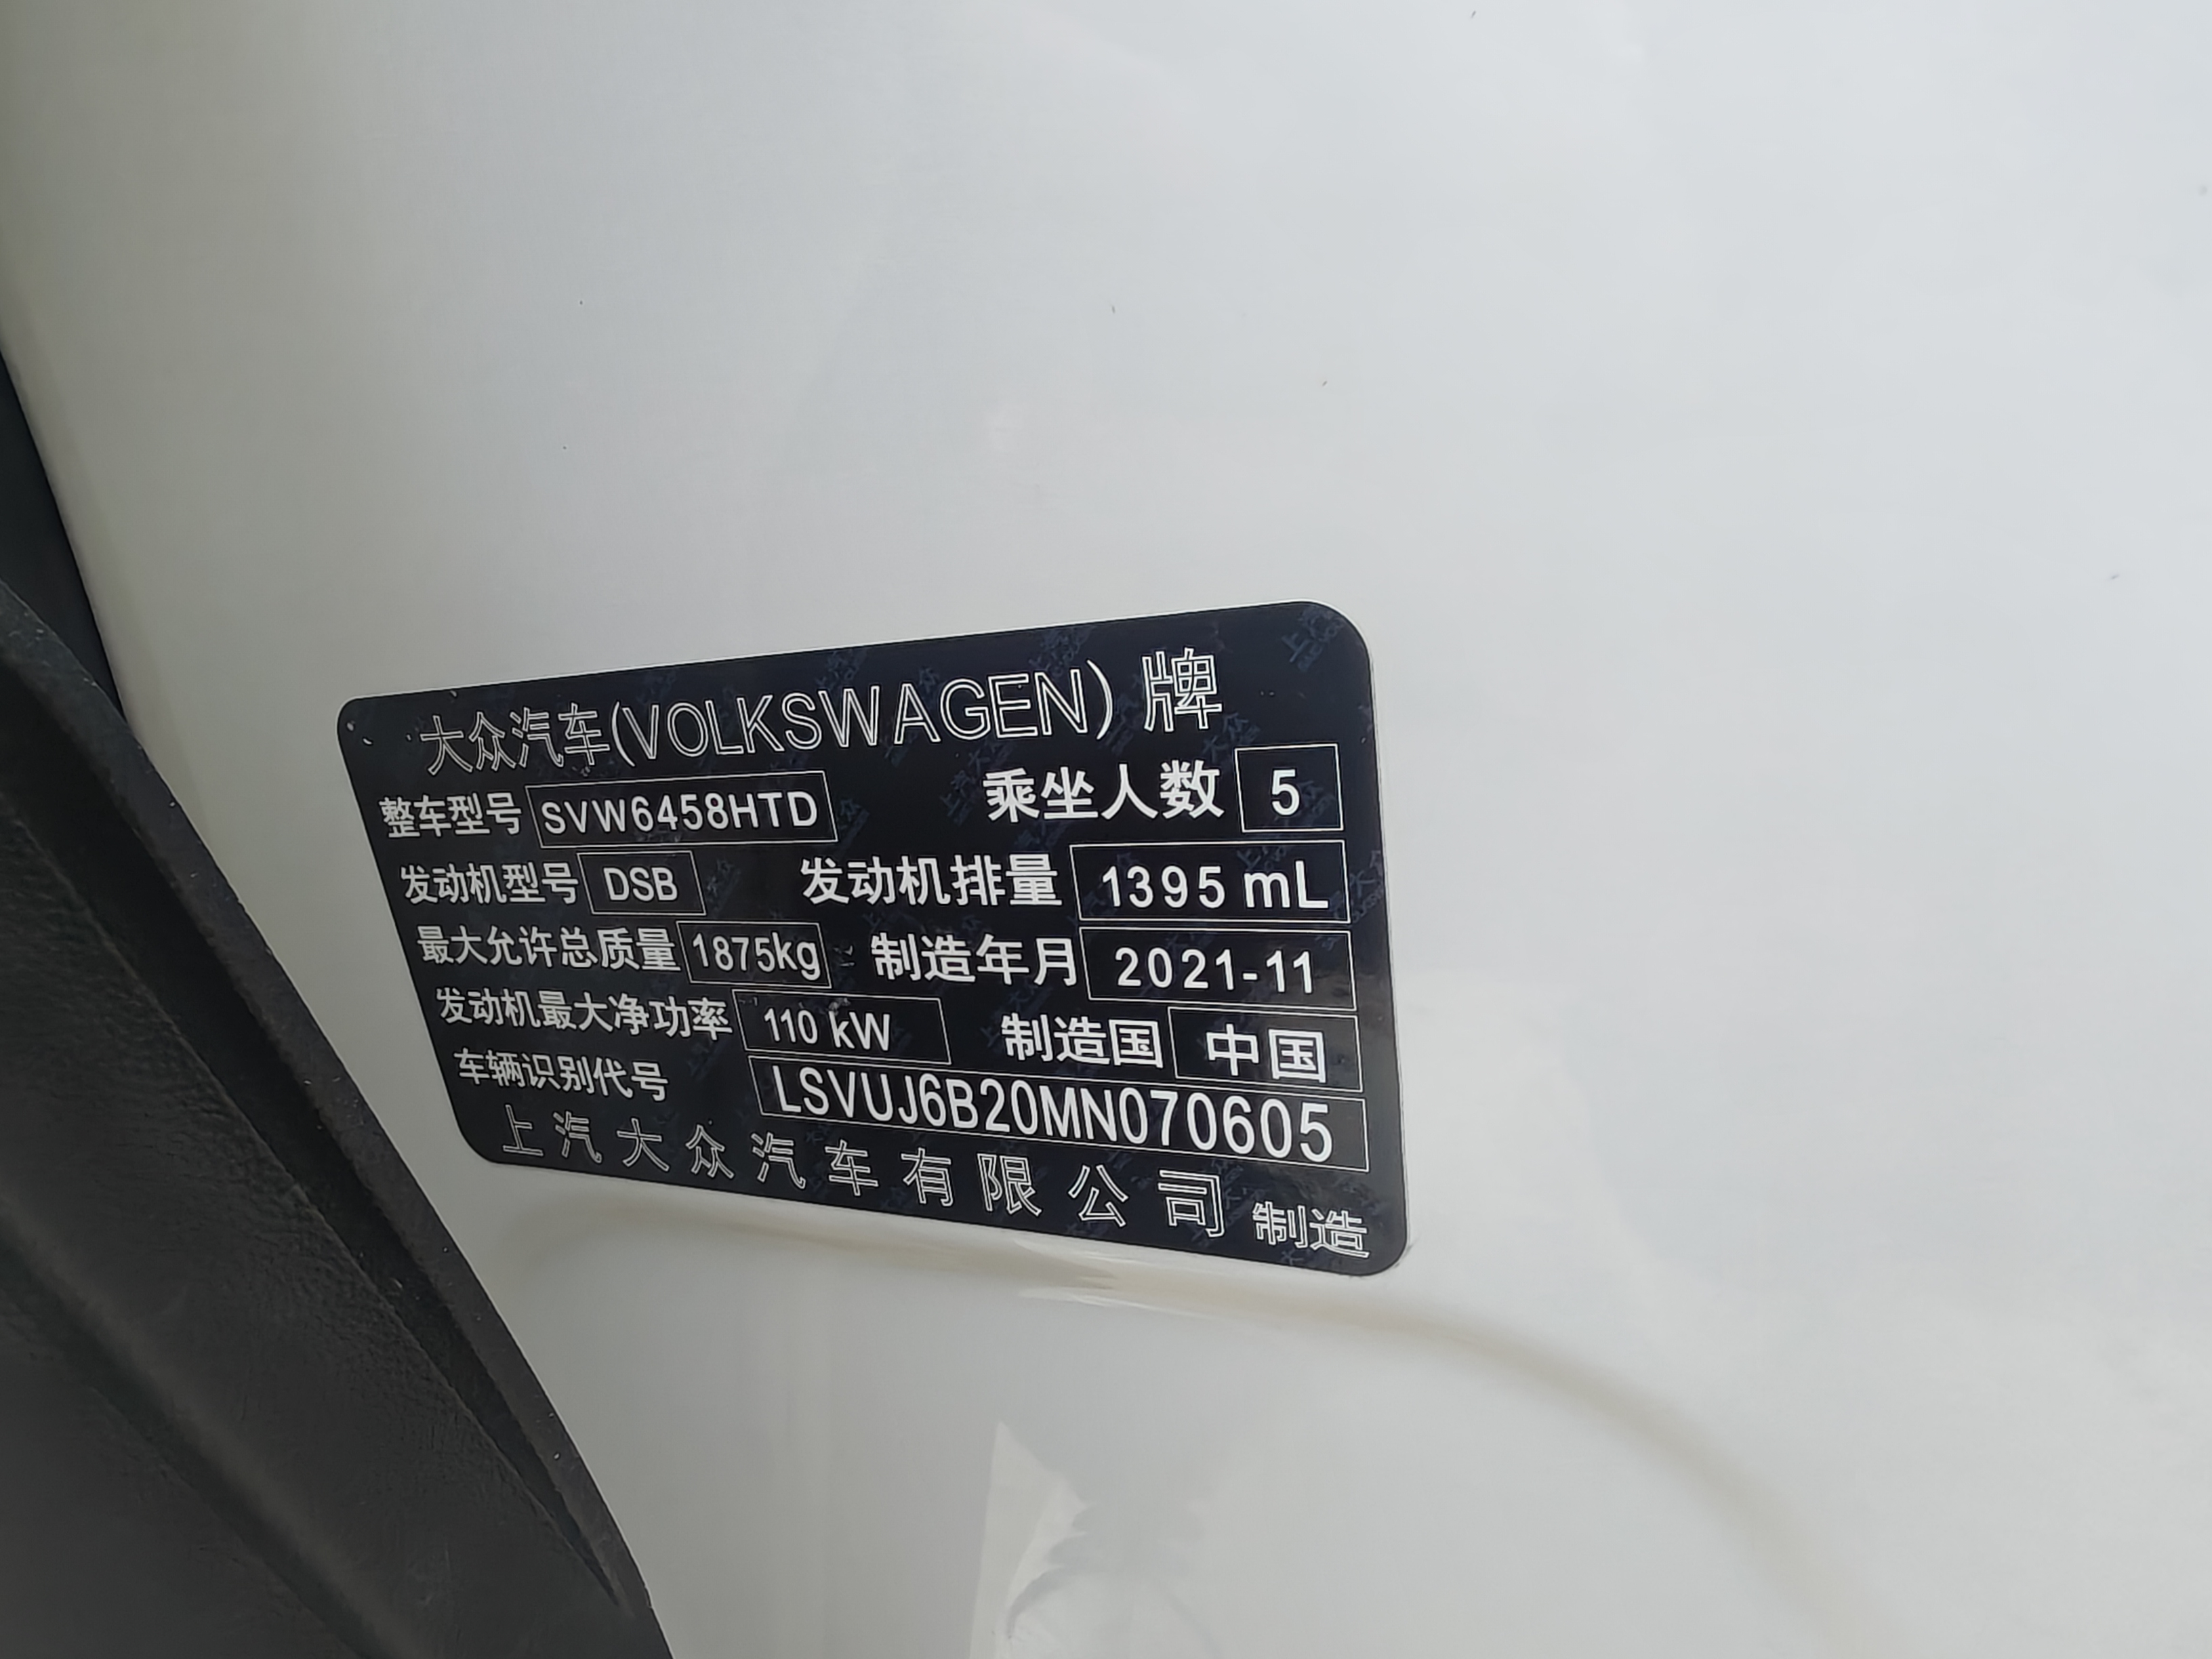
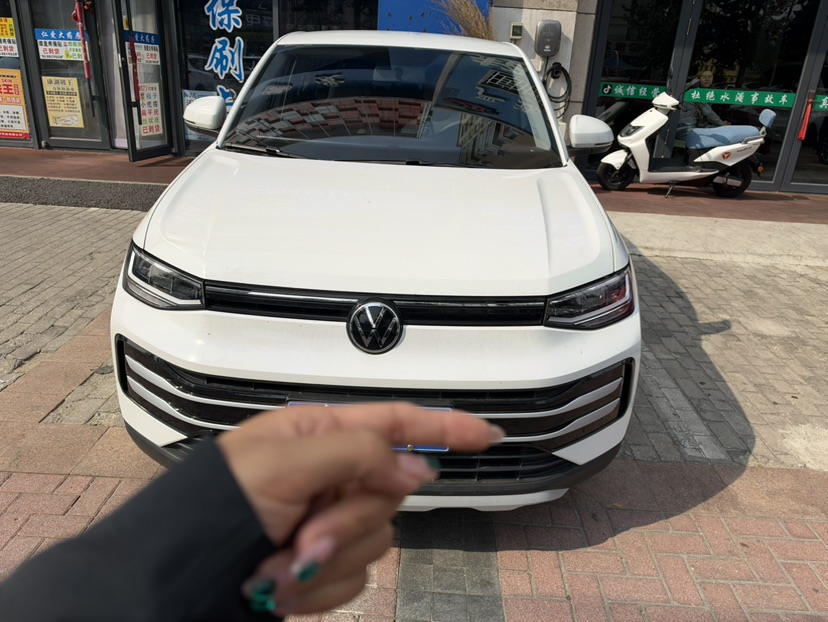
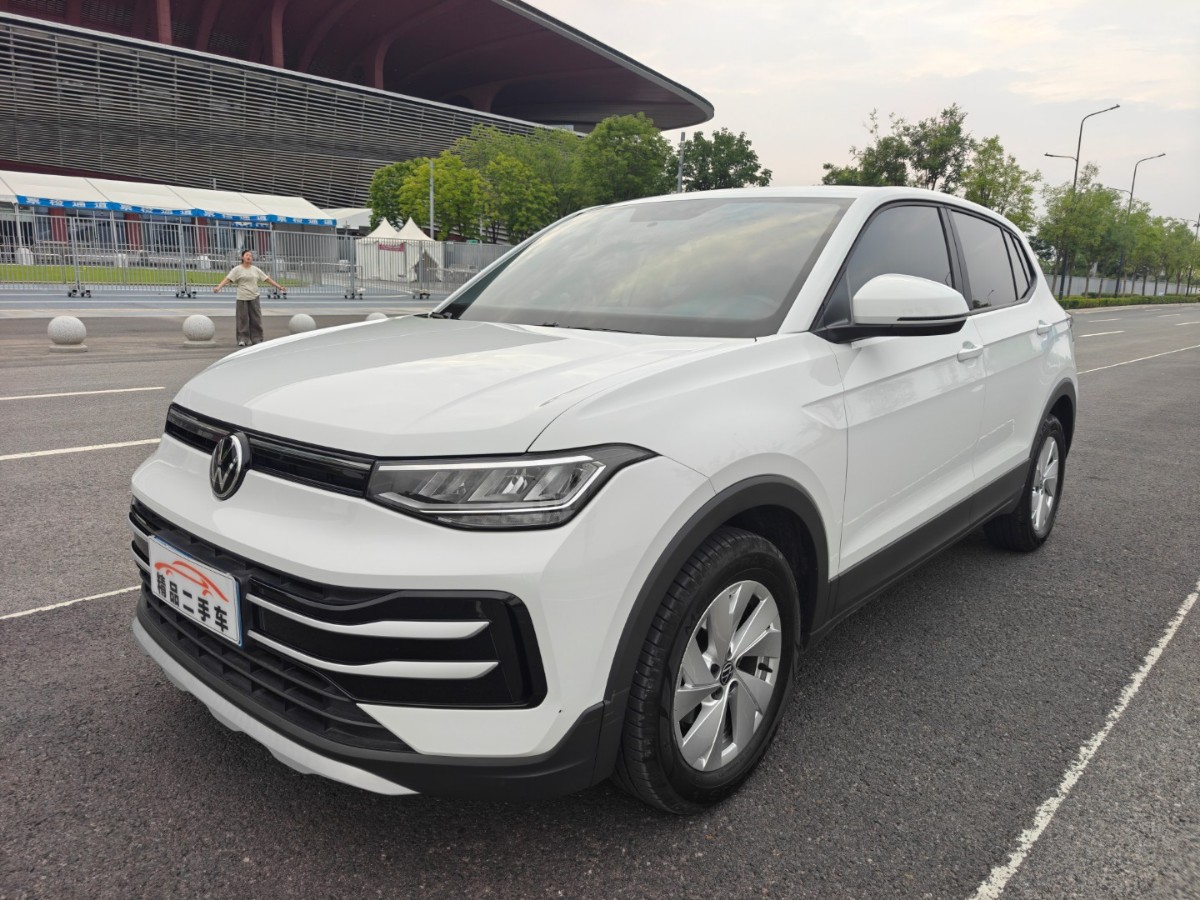
BrandVolkswagen
SeriesTharu
Year2022
First Registration2022/02
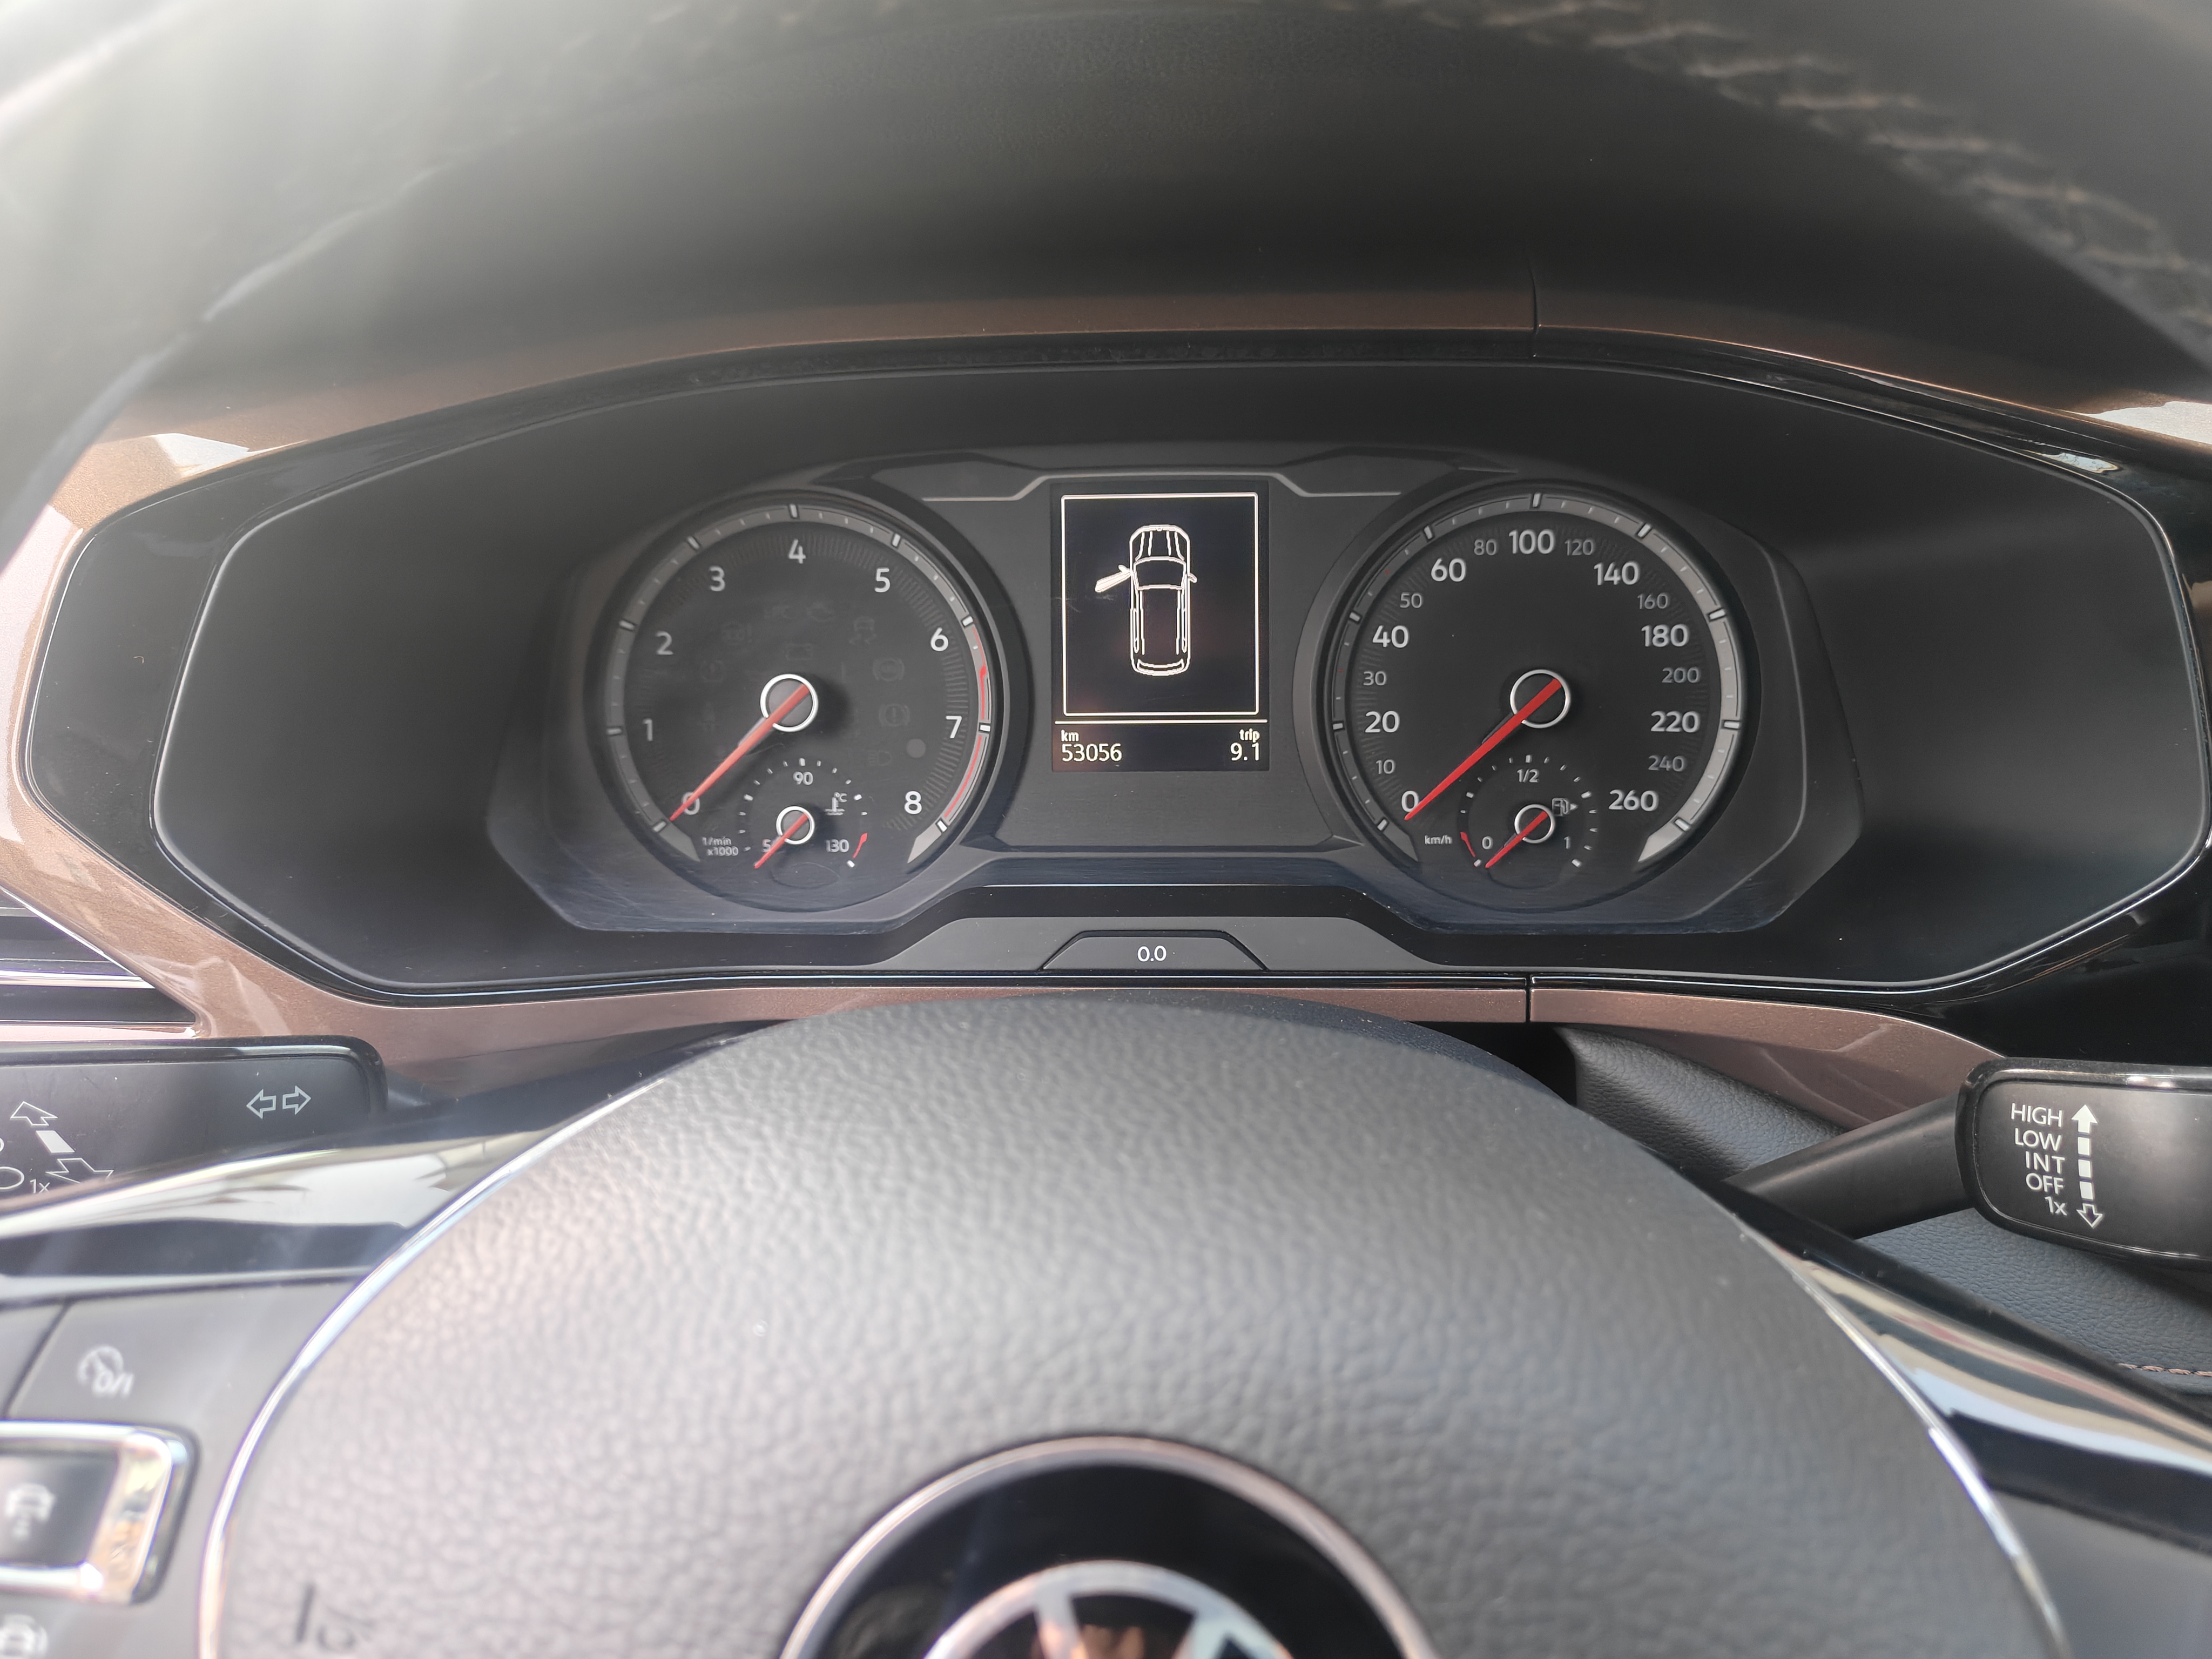
Mileage5.3km
Transfer Count-
FuelGasoline
TransmissionDCT
Engine1.4T 150 L4
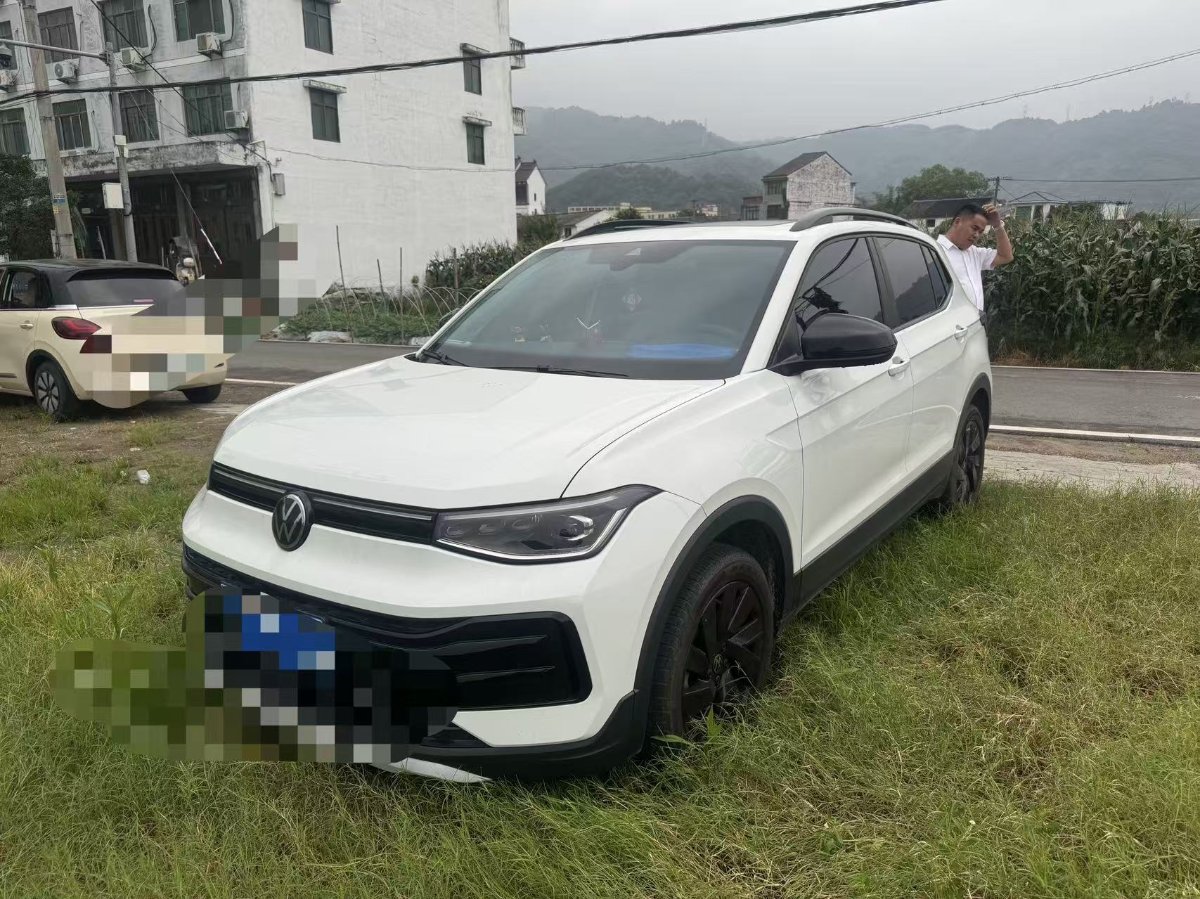
ColorWhite
Seats-

Condition Description

Left rear leaf section supplementary table, 2 keys, green book unzipping in progress.

Configuration Highlights

✓Driver/Passenger Airbags
✓Front/Rear Side Airbags
✓Front/Rear Curtain Airbags
✓Tire Pressure Monitoring
✓ISOFIX Child Seat Anchors
✓Keyless Start System
✓Keyless Entry System
✓ABS Anti-lock Braking
✓Electronic Brake Distribution
✓Electronic Stability Control
✓Hill Start Assist
✓Auto Hold
✓Panoramic Sunroof
✓Roof Rack
✓Multifunction Steering Wheel
✓Seat Material
✓Driver/Passenger Power Seats
✓Rear Cupholders
✓GPS Navigation
✓Low Beam Headlights
✓Daytime Running Lights
✓Auto Headlights
✓Adjustable Headlight Height
✓Power Windows
✓Anti-pinch Windows
✓Climate Control Type
✓Rear Air Vents
✓Start-Stop System
✓Active Safety System

Q&A

More

Can the three electric systems (battery, motor, electronic control) of Chinese EVs be repaired by third parties overseas?

Currently, in most developing countries, there is a severe lack of deep repair capabilities for the three electric systems. We recommend that B2B car dealers must have basic electrical insulation testing capabilities.
For countries with strict anti-dumping laws, do the low-priced used new energy vehicles you export face the risk of being confiscated by customs on the grounds of dumping?

This is a macro policy minefield. Although used cars are rarely classified as dumping, if your single import quantity is too large and the declared price is significantly lower than local similar products, it can easily trigger an investigation by the tax bureau. We strongly recommend B2B buyers to break down shipments into smaller batches and use multiple invoices for customs clearance.

If the customs of the destination country values the vehicle higher than your commercial invoice amount, leading to a surge in duties, who is responsible?

The customs of the destination country has the right to disregard the commercial invoice and reassess the value based on its internal database (such as the customs valuation red book). Any additional duties incurred are a result of the importing country's policy and are fully borne by the buyer (importer).